
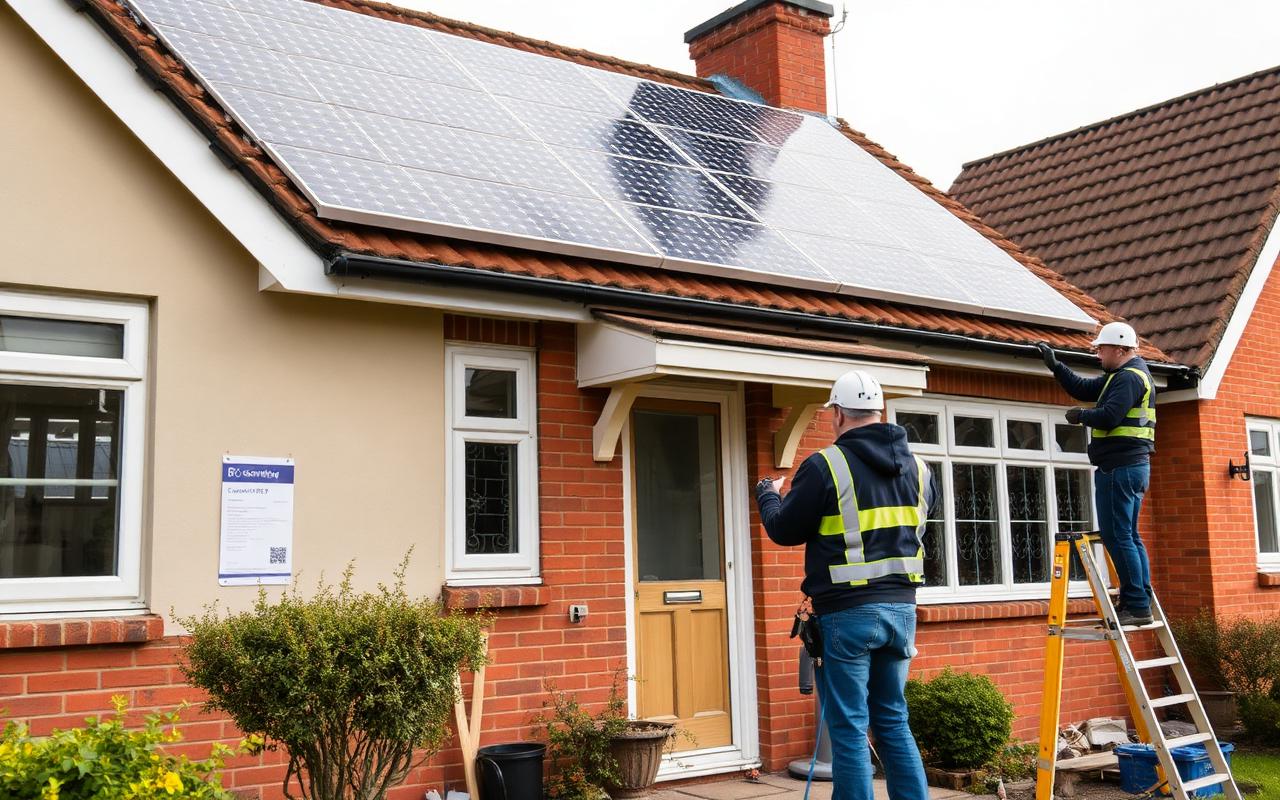
A rating target can turn into a cashflow problem very quickly. One letter on an EPC certificate can mean insulation works, new heating systems, replacement windows or ventilation upgrades - and very few landlords want to wait months for a bank decision while a property sits underperforming. That is why epc upgrade funding has become a live issue for landlords who need to keep properties lettable, compliant and commercially viable.
The real challenge is not just paying for the work. It is finding the right type of funding for the size of the job, the urgency of the deadline and the way your portfolio already operates. A landlord with one buy-to-let in decent condition has a different problem from an HMO operator trying to improve several properties before the next letting cycle. Treating every case the same is where expensive decisions get made.
Why EPC upgrade funding matters now
For most landlords, EPC works are not cosmetic. They affect tenant demand, operating costs and, in some cases, the ability to let or refinance a property on good terms. If a home is harder to heat, it becomes less attractive to tenants. If the rating is too low, the property may need work before it fits your long-term plans.
There is also a timing issue. EPC improvements often arrive alongside other costs rather than on their own. A void period, a boiler failure, a tax payment or a refinance delay can easily land in the same quarter. Even landlords with healthy equity can still be short on ready cash. That is why funding speed matters just as much as pricing.
The main EPC upgrade funding options
Landlords usually have four realistic routes. The right one depends on how quickly you need the money, how much admin you can tolerate and whether you want more debt on the balance sheet.
Savings or retained rental income
If you have cash reserves, this is usually the simplest answer. There is no lender process, no underwriting and no extra monthly commitment. For smaller works such as loft insulation, smart heating controls or selective glazing upgrades, using retained profit can make sense.
The drawback is obvious. Cash tied up in EPC works is cash you cannot use elsewhere. If another property needs urgent repairs next month, or a purchase opportunity comes up, your liquidity is gone. For landlords running lean by choice, paying outright is not always the most commercial option.
Further advances or remortgaging
This can work well if the property has enough equity, your lender is supportive and you are not under pressure on time. Mortgage-backed funding may offer a lower headline cost than short-term finance, especially for larger projects.
But it is often slow. Valuations, legal work, underwriting and affordability checks can drag on. It also adds conventional debt, which may not suit landlords who are trying to protect borrowing capacity for acquisitions or refinancing elsewhere. If the EPC work is urgent, waiting for a mortgage process can create more risk than it solves.
Unsecured business borrowing
Some landlords use unsecured loans or business credit to cover upgrade costs. This can be faster than a remortgage and useful for mid-sized works.
The trade-off is that pricing can be higher, approvals can be inconsistent and the structure still sits as debt. Credit profile often plays a big part too. If your goal is speed with minimal friction, unsecured lending does not always deliver it.
Receivables-based funding tied to rental income
This option is increasingly relevant for landlords because it is built around the income the asset already generates. Instead of taking on a conventional loan, you access capital against future rental income. For landlords who need funding quickly and do not want another debt facility complicating the picture, this can be a strong fit.
It is particularly useful when the works are practical, time-sensitive and likely to protect or improve the property’s performance. If the rental income is solid, the funding decision can often be much more straightforward than with a bank-led process.
What landlords are actually paying for
When people talk about EPC upgrades, they often imagine one big refurbishment. In practice, many properties need a targeted package of works rather than a full strip-out. Funding may be used for insulation, heating upgrades, hot water improvements, draught proofing, extractor systems, glazing or a more efficient boiler.
The cost range varies sharply. A straightforward uplift may only require a few thousand pounds. A tired older property can need a much more serious spend, especially if multiple measures are needed to move the rating enough to matter. That is why landlords should avoid generic advice. The funding structure needs to match the works plan, not the other way round.
How to choose the right EPC upgrade funding
The first question is speed. If your property is between tenancies, your builder is ready and you need to move now, slower funding can be false economy. A slightly cheaper facility that arrives six weeks too late may cost you more in lost rent and project drift than a faster option.
The second question is balance-sheet impact. Some landlords are comfortable adding debt if the cost is competitive and the timeline works. Others want to preserve borrowing lines for purchases, major refurbs or tax planning reasons. If keeping conventional debt lower matters to you, the funding route should reflect that.
The third question is certainty. There is no value in starting applications across three lenders only to find each one wants more documents, more time and stricter criteria than expected. Landlords usually do better with funding that aligns with how their business actually performs - especially where rental income is strong, but taxable profits or personal income do not tell the full story.
EPC upgrade funding and the case for speed
Landlords tend to underestimate the cost of delay. A vacant property waiting for finance is not just standing still. It is absorbing council tax, insurance, standing charges and lost rent. If contractors have been lined up, missed start dates can also push the whole job back.
That is where specialist funding earns its place. A fast decision and rapid payout can be the difference between improving a property in one void period or losing another month of income. For landlords juggling several units, that timing can affect the whole portfolio.
This is also why many property investors prefer funding that is designed around rental assets rather than consumer-style underwriting. The asset is producing income. The works support that income. The structure should make commercial sense on those terms.
When a non-loan structure makes sense
For landlords who do not want to add another conventional loan, a receivables-based model can be a cleaner solution. Factored, for example, provides funding by purchasing future rental income rights rather than issuing a standard loan. That matters if you want access to capital for EPC works without the drag of a traditional debt product or a hard credit-led process.
This type of funding will not suit every scenario. If you are planning a very large project over a long timeline, or if a refinance is already progressing smoothly, another route may be more economical. But where the need is immediate and the property already has dependable rent coming in, speed and simplicity often outweigh the appeal of a slower, more rigid facility.
What to prepare before you apply
Whatever route you choose, being organised improves your options. Lenders and specialist funders want to understand the property, the income and the purpose of the capital. If you can show current rent, tenancy position, expected upgrade costs and the reason the works are needed, you are far more likely to keep the process moving.
It also helps to be realistic about scope. If your contractor says the work may uncover more issues once the property is opened up, build some contingency into the amount you seek. Underfunding an EPC project is a common mistake. A half-finished efficiency upgrade rarely solves the underlying problem.
Landlords should also think beyond compliance. Better EPC performance can support stronger tenant demand, lower running costs and a more marketable asset. Not every pound spent will produce a dramatic uplift, but well-chosen works can protect income and reduce future friction.
The best funding decision is not always the cheapest on paper. It is the one that gets the work done at the right time, with the right amount of certainty, and without creating a bigger problem elsewhere in your business. If your property needs attention now, waiting for the perfect facility can be more expensive than securing the practical one and keeping the asset moving.